Insurance for Paper GCs: How General Contractors Who Sub Out the Work Stay Protected
The short answer What insurance does a paper GC need? A paper GC, a general contractor that subcontracts all or nearly all of the field work, still needs general liability, workers’ compensation, umbrella or excess limits, and usually builder’s risk and bonding. The difference is where the risk sits. A paper GC’s protection depends less […]
AI in Contractor Insurance: Why Agentic Tools Work Best With Human Advisors
The short answer Is AI changing contractor insurance? Yes. AI and agentic AI tools now speed up quoting, certificate tracking, document review and claims intake across the insurance industry. But contractor insurance is full of exceptions: class codes, exclusions, subcontractor requirements and hard-to-place risks. That is where software alone can leave contractors exposed, and where […]
WIP Schedules and Your Insurance Program: What Do Underwriters Read Between the Lines?
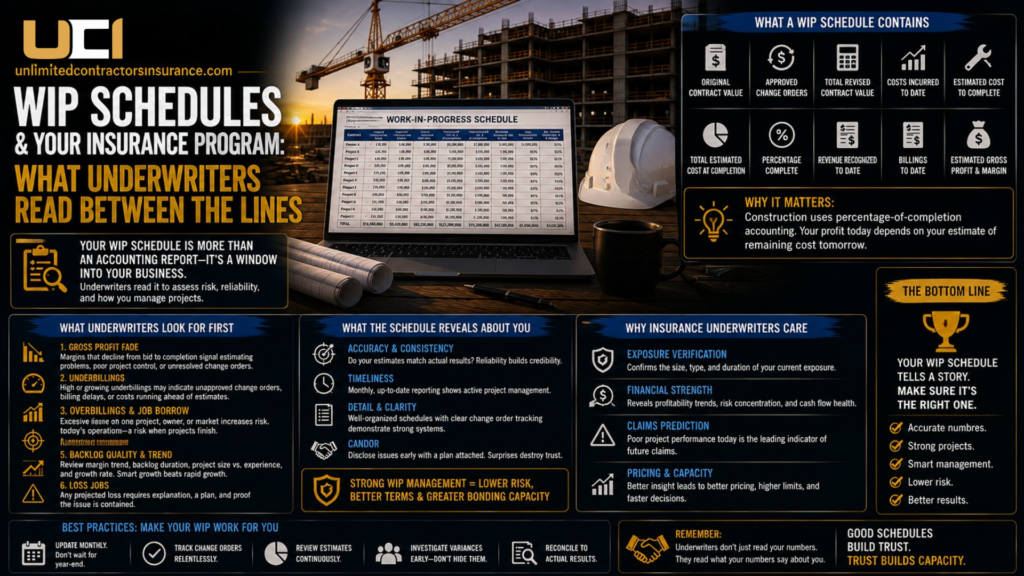
Most contractors treat the work-in-progress schedule as an accounting requirement. Your CPA needs it. Your surety asks for it. You produce it and move on. But in construction WIP schedule underwriting, that document can reveal far more about your business than many contractors realize. Underwriters read it differently. To them, the WIP is the most […]
Contractors Professional and Pollution Liability: The Design-Build Gap
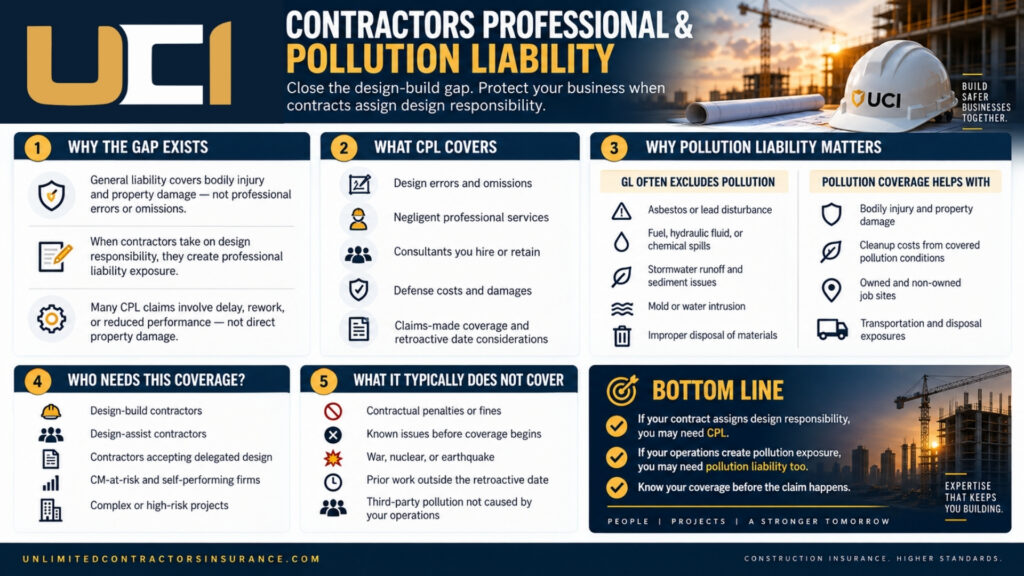
Your general liability policy covers bodily injury and property damage. It does not cover professional negligence. That distinction rarely mattered when contractors built what architects designed. It matters enormously now, because delivery methods have changed. Design-build, design-assist, delegated design, and construction management at risk all place design responsibility on the contractor — and general liability […]
Builders Risk on Complex Projects: LEG Clauses, Soft Costs and Delay in Start-Up
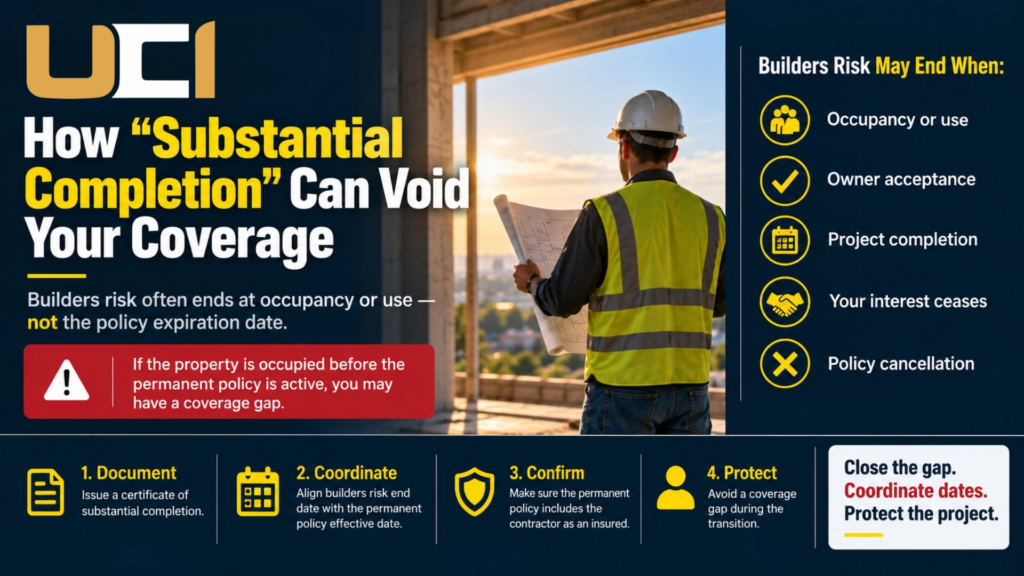
On a straightforward project, builders risk is a simple product. Insure the structure, insure the materials, cover the usual perils, done. On a complex project, it becomes one of the most negotiated placements in the program — and the negotiations that matter most are not about limits or premium. They are about three things. Which […]
What Are Subcontractor Default Insurance vs. Subcontractor Bonds: Which Protects a Large GC?
Every general contractor faces the same exposure. You sign a prime contract promising to deliver a project. Then you hire subcontractors to perform most of the work. If one of them fails, you still owe the owner a finished building. Two products address that risk, and they work in fundamentally different ways. Subcontractor bonds transfer […]
Marketing a Middle-Market Construction Program: The 120-Day Renewal Timeline
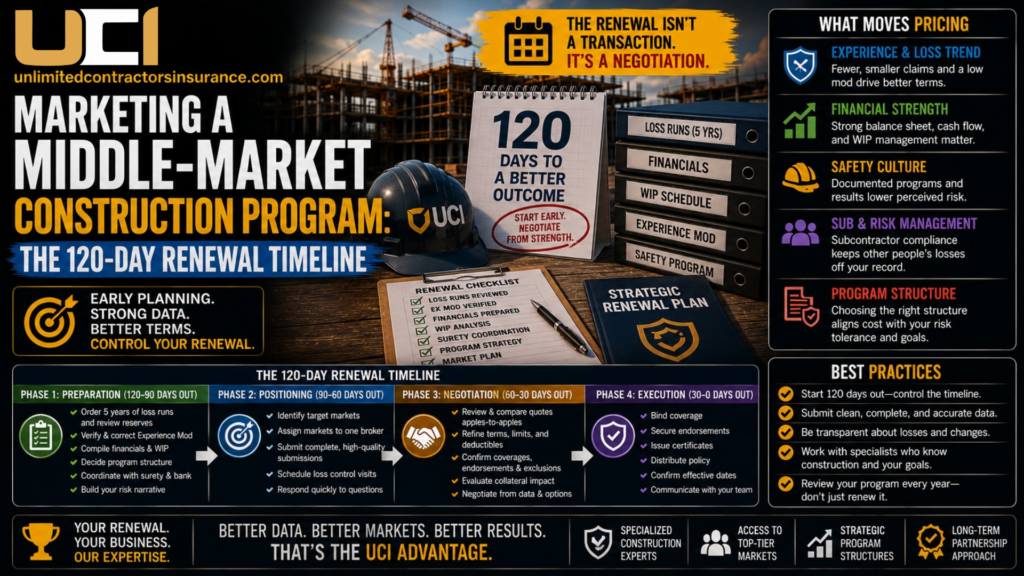
A small contractor’s renewal is a transaction. A middle-market construction program is a negotiation. That distinction changes everything about how you approach it. Underwriters at this level are not rating an application. They are evaluating a business, forming a view on its management, and deciding how much of their capacity to commit. Those decisions take […]
Roofing Insurance Coverage Types for Commercial Roofing Contractors
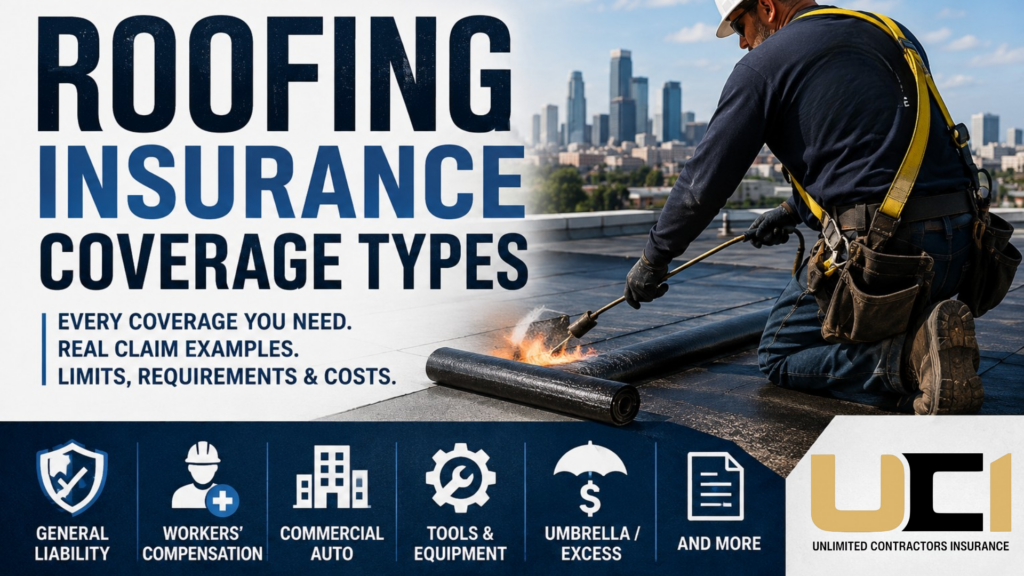
Commercial roofing contractors buy a program, not a policy. A single roofing operation running $5M or more in annual revenue typically carries six core coverage types, and larger operations layer on five or six more that never appear on a small contractor’s certificate. This guide covers every coverage type a commercial roofing contractor needs, what […]
Large Deductible and Loss-Sensitive Programs: When a Contractor Should Make the Switch

Most contractors buy insurance on a guaranteed cost basis. You pay a fixed premium. The carrier pays the claims. Your cost is set before the year begins. That structure works well early on. But it stops working once your losses run better than your rate assumes. At that point, you are funding someone else’s claims. […]
Total Cost of Risk: What $1M+ Contractors Measure Instead of Premium
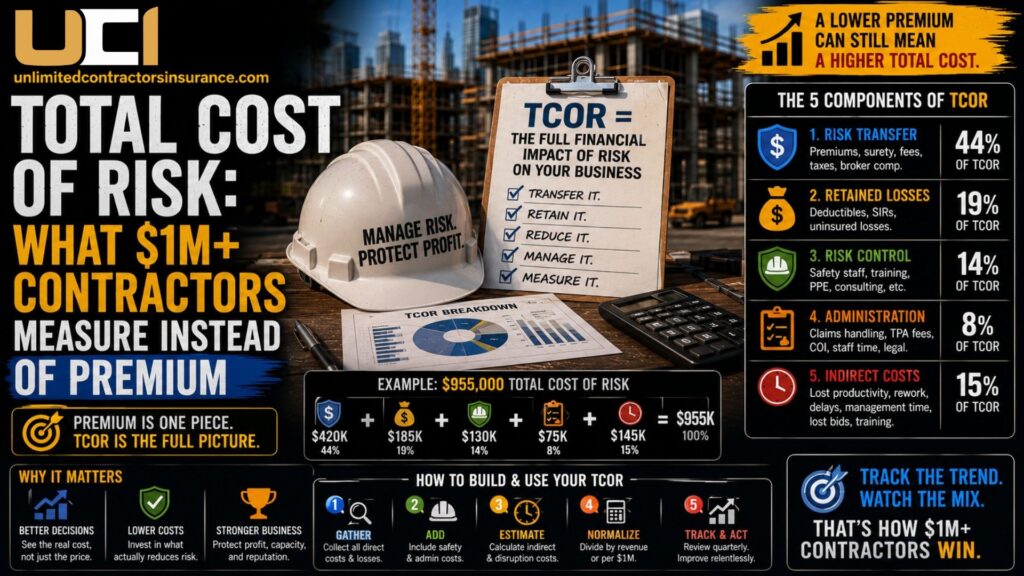
Most contractors judge their insurance program by one number. They look at the premium, compare it to last year, and decide whether they did well. That number is incomplete. For a contractor above roughly $1 million in revenue, premium is only one part of what risk actually costs the business. Deductibles, safety spending, claims administration, […]